Dynamic, Forward-Looking
Default Prediction.

Credit risk moves daily — but agency ratings don't. The gap between a firm's actual creditworthiness and its last agency rating can persist for months, leaving portfolios exposed to risk that static scores fail to capture.

Criat Probability of Default (PD) quantifies a firm's default likelihood from 1 month to 5 years; PD-implied Rating (PDiR) maps it to a letter-grade scale directly comparable to agency ratings — but updated daily.

When ratings stand still, risk doesn't.
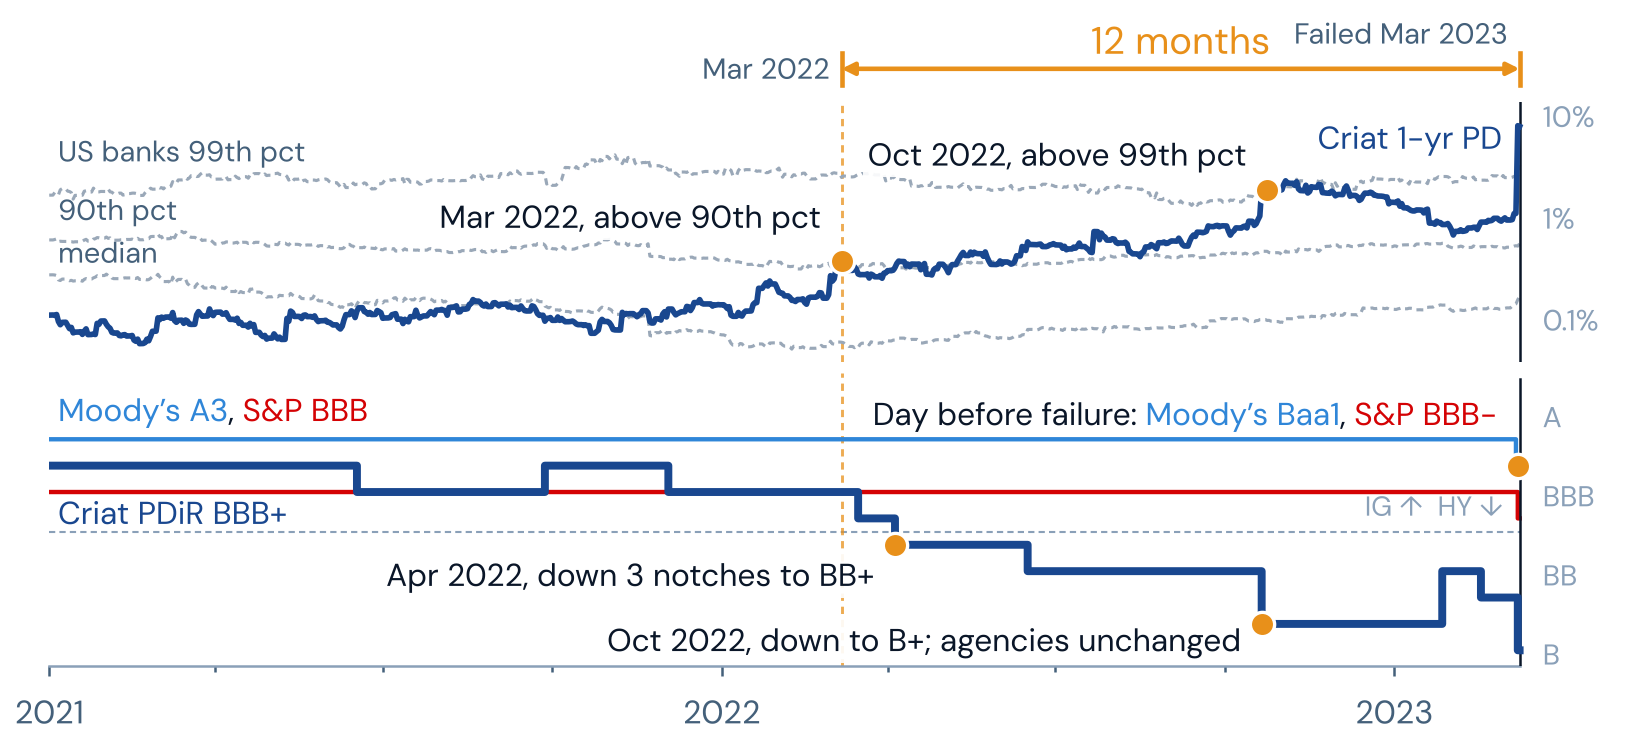
Silicon Valley Bank: Criat's 1-year PD against US bank percentiles, and Criat's PDiR against agency ratings, 2021 to March 2023

Silicon Valley Bank held investment-grade ratings from both Moody's and S&P until the day it collapsed.

MAR–APR 2022
PDiR drops 3 notches to BB+. PD crosses the 90th percentile of US banks.
OCT 2022
PDiR deteriorates to B+. Agency ratings unchanged.
10 MAR 2023
SVB fails. The day before: Moody's Baa1, S&P BBB−.
12
months ahead — while agency ratings stayed investment grade

PDiR is a model output, not a credit rating issued by a registered credit rating agency.

Every firm, every horizon, every day.

140,000+
Firms Covered
1–60mth
Term Structure
Daily
Update Frequency
35+
Years of History
By Universe
Public Firms 94,000+
Private Firms 46,000+
Bond Issuers 22,000+
Financial Firms 25,000+
By Region
Asia Pacific 55,000+
North America 45,000+
EMEA 36,000+
Latin America 4,000+

Analyse, integrate, or both.

Criat iRAP — BayWa AG

PD data flows into your existing risk infrastructure — whether you analyse interactively, integrate via feeds, or access natively within partner platforms.

iRAP Web Application
Interactive analysis — PD charts, driving factors, financial analysis, what-if analysis. Global Plus, China, and X editions.
Data Feeds
SFTP, API or MCP — integrate PD, PDiR, and related metrics into your systems and models.
Partner Platforms
Access Criat data natively within FactSet or Snowflake — embedded in your existing workflow.

The science behind every metric.

Criat's Probability of Default is produced by the Forward Intensity Model (FIM) — a third-generation credit risk model built on econometrics and refined with machine learning.

3rd Generation — 2010s

Forward Intensity Model

Dynamic, forward-looking. Built for all firm types and markets.

1st Gen — 1970s Scorecard Expert-driven scoring — foundational and still widely used. Does not respond to macro or market condition changes; reassessed periodically.
2nd Gen — 1980s Structural Model Merton-based distance-to-default from market value and debt. A significant advance; less effective for Asian and emerging-market firms, and for financial firms.

What makes it different

The Forward Intensity Model is a single framework that produces daily, forward-looking default probabilities — across all horizons, firm types, and markets.

01
Hybrid information set — goes beyond any single data source. Default prediction improves when macro conditions, firm fundamentals, and market signals are modelled jointly.
02
Survival-default dependency — a firm's default risk in month three is conditional on its surviving months one and two. Modelling this dependency produces a coherent PD term structure, not isolated point estimates.
03
Granular segmentation — one global model does not fit all. Region-sector calibration with advanced dimension reduction mitigates default scarcity in smaller segments.

How the models are built

Each model draws from up to four risk factor dimensions — macro-financial conditions, firm-specific financial ratios, equity-based factors, and bond-based factors — combined based on data availability and market characteristics.

Public Firm Models

The foundation. 16 risk factors — level and trend used jointly to capture momentum and directional shifts. Calibrated separately by region and sector.

Macro-Financial
Financial Ratios
Equity-Based
Private Firm Models

Extends the Public Firm framework to unlisted companies. Equity-based factors are proxied, producing PDs directly comparable with those of public firms.

Macro-Financial
Financial Ratios
Equity-Based (proxied)
China Bond Issuer Models

Purpose-built for China's onshore and offshore bond markets, where equity data alone is less informative and local macro dynamics diverge from global patterns.

Macro-Financial
Financial Ratios
Equity-Based
Bond-Based
Calibration

Trained on a meticulously curated default database. Default definition aligned with Big 3 rating agencies — covering bankruptcy, missed payments, and distressed exchanges.

20,000+
Default Events
7,600+
Default Firms

Calibrated across North America, Europe, APAC Developed, Emerging Markets, China, and India — separately for Corporate and Financial sectors.

6 regions × 2 sectors
Validation

Criat's in-sample and out-of-sample Accuracy Ratios (AR) are consistent — indicating that the model generalises beyond its training data rather than overfitting.

Criat Structural model provider
84%
82%
North America
72%
68%
Europe
75%
60%
APAC Developed
75%
60%
Emerging Markets
Data Sources
The Forward Intensity Model (FIM) has been adopted by the IMF, AMRO and MAS for their public policy work.
IMF
FSAP, GFSR
since 2016
AMRO
Annual Consultation Report
since 2019
MAS
Financial Stability Review
since 2021

See what dynamic PD reveals in your portfolio.

Talk to Our Experts