
Singapore, 24 May 2024 — We are proud that the Bottom-up Default Analysis (BuDA) framework, co-developed by Criat's founders, continues to support the International Monetary Fund (IMF), this time to simulate projected probabilities of default (PD) in the latest Global Financial Stability Report.
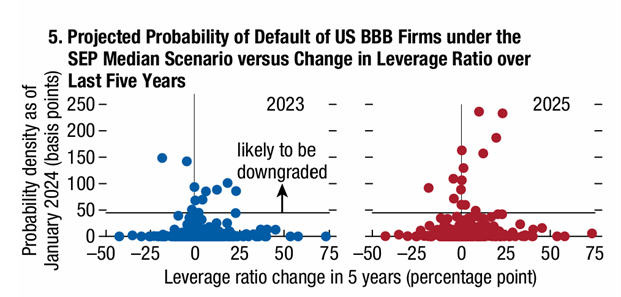
The framework was used to simulate the projected PD of US BBB-rated firms under the median scenario of the Federal Reserve's Summary of Economic Projections (SEP), against the change in their leverage ratio over the last five years.
Criat offers the commercial version of this framework for financial institutions, insurers and asset managers worldwide.
BuDA was co-developed by Criat's two founders, Prof Duan Jin-Chuan and Dr Miao Weimin, with IMF Senior Economist Dr Jorge Chan-Lau, and with active support from the Credit Research Initiative (CRI) team at the National University of Singapore. The framework has since been enhanced to version 3.5.1.
See the April 2024 report: Global Financial Stability Report, April 2024: The Last Mile — Financial Vulnerabilities and Risks, IMF